


The Global Reporting Initiative (GRI) has submitted its official response to EFRAG’s public consultation on draft European Sustainability Reporting Standard 40a (ESRS-40a), calling on European regulators to recognize established global reporting frameworks to prevent administrative duplication for non-EU corporations.
Drafted under Article 40a of the EU Corporate Sustainability Reporting Directive (CSRD), ESRS-40a sets out impact-based sustainability reporting requirements for non-EU entities with annual EU revenues exceeding €450 million and local subsidiary or branch turnover exceeding €200 million.
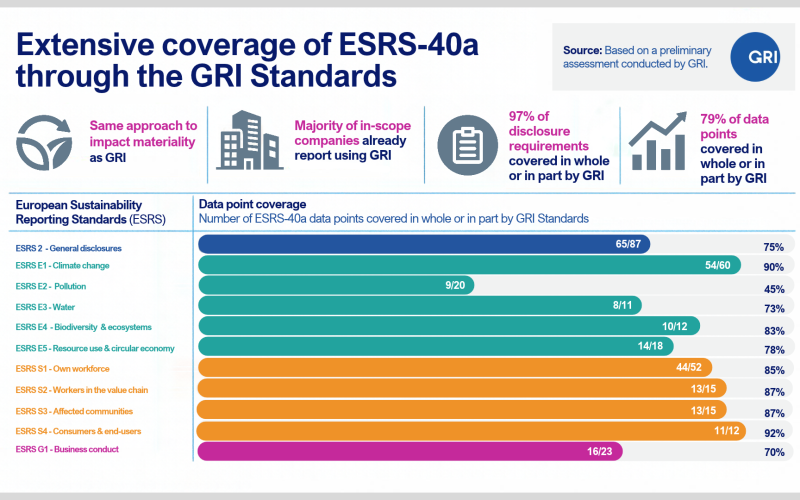
GRI noted that its standalone research indicates the GRI Standards cover 97 per cent of draft ESRS-40a disclosure requirements and 79 per cent of its specified data points.
Unlike the core ESRS standards for EU-headquartered firms, which enforce double materiality covering both financial risks and environmental impacts, ESRS-40a focuses exclusively on impact materiality—a structural focus shared with the GRI framework.
GRI outlined three core recommendations to EFRAG to streamline compliance:
- Direct compliance recognition: Allow non-EU companies to reference existing assured GRI disclosures prepared on global perimeters to satisfy ESRS-40a obligations.
- Formalized interoperability: Issue clear cross-mapping guidelines detailing structural alignment between ESRS-40a and GRI standards across environmental, social, and governance topics beyond climate.
- Global market level playing field: Maintain consistent impact reporting rules to preserve comparability across international capital markets for companies already disclosing under GRI.
Robin Hodess, Chief Executive Officer of GRI, stated that building upon established international reporting practices ensures the EU achieves its corporate transparency objectives without placing unnecessary administrative demands on global businesses.
Susanne Stormer, Chair of the Global Sustainability Standards Board (GSSB), added that aligning assured GRI impact disclosures with ESRS-40a puts interoperability into practice, benefiting the majority of target non-EU corporations that already use GRI disclosures—including over 80 per cent of large firms in China and more than 70 per cent in Japan, South Korea, and Switzerland.
EFRAG’s public consultation on the ESRS-40a Exposure Draft remains open for stakeholder feedback through 31 October.